Market overview of the Direct Current (DC) Load Bank Market
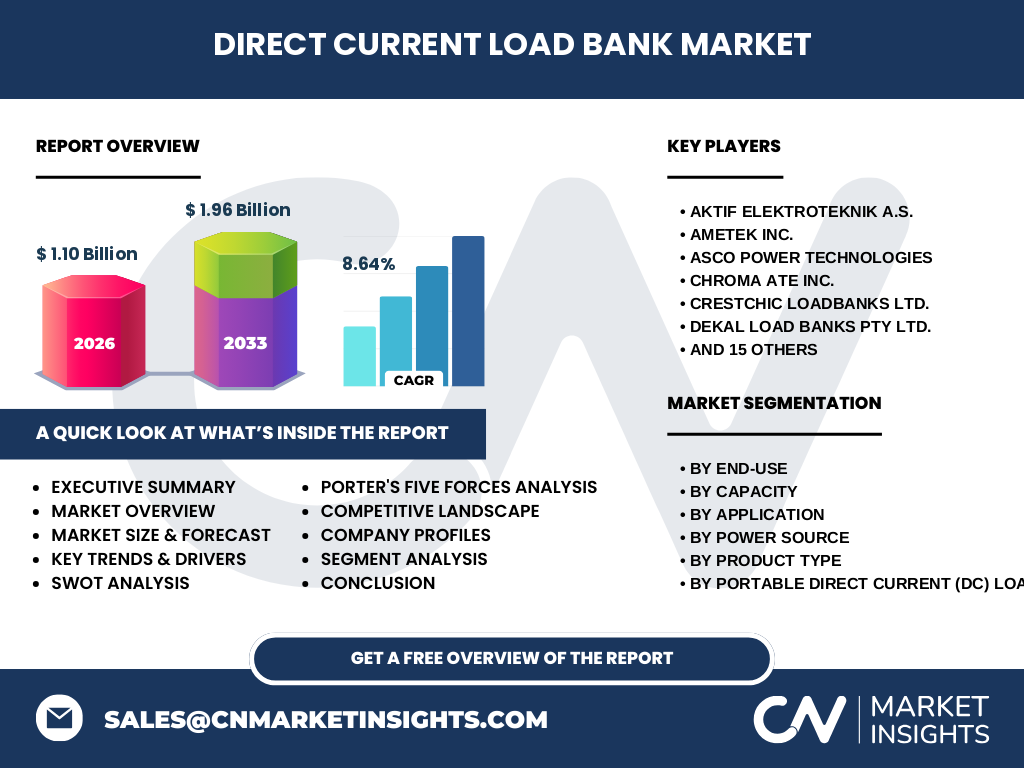
The Direct Current (DC) Load Bank Market encompasses specialized electrical test equipment designed to simulate exact electrical loads for DC power systems. Valued at 1.10 Billion in 2026, this sector ensures critical power infrastructure operates reliably by validating battery banks, rectifiers, and solar arrays against catastrophic failure under controlled thermal stress conditions.
Key market drivers, restraints, challenges, and opportunities shaping Direct Current (DC) Load Bank Market
Market expansion is primarily propelled by the exponential growth of hyperscale data centers requiring rigorous backup verification. However, supply chain bottlenecks for high-grade nickel-chromium resistance wire constrain manufacturing output. A major opportunity lies in integrating smart IoT monitoring capabilities into high capacity stationary units for automated predictive maintenance.
Emerging trends and growth patterns in Direct Current (DC) Load Bank Market
A definitive shift toward modular, trailer-mounted DC load banks is reshaping field testing logistics. Telecommunications operators increasingly demand compact, rack-mounted solutions to test distributed power plants efficiently. Industry trends show a heavy preference for regenerative testing technologies that feed energy back into the grid rather than wasting it as thermal heat.
COVID-19 impact analysis and recovery trajectory
The pandemic initially disrupted global supply chains for critical components like specialized circuit breakers and cooling fans, delaying delivery schedules for key manufacturers. Recovery has been robustly accelerated by post-pandemic digital infrastructure investments, pushing the Direct Current (DC) Load Bank Market industry trends toward automated remote testing protocols that minimize onsite technician exposure.
Competitive landscape and strategic dynamics
The competitive ecosystem features established engineering leaders such as AMETEK Inc., Eaton Corporation plc, and Schneider Electric SE alongside specialized providers like Crestchic Loadbanks Ltd. and Mosebach Manufacturing Company. Market concentration is moderate, with top tier players leveraging global distribution networks and customized engineering capabilities to secure lucrative long-term enterprise service contracts.
Executive summary of the Direct Current (DC) Load Bank Market
Our proprietary research indicates that the Direct Current (DC) Load Bank Market market size is positioned for exceptional expansion, driven by widespread electrification and data center proliferation. Valued at 1.10 Billion in 2026, the market is projected to reach 1.96 Billion by 2033, expanding at a robust CAGR of 8.64% over the forecast period.
Market forecast from 2027 to 2033
Driven by accelerating renewable energy integration and stringent grid reliability standards mandated by bodies like NERC, the market will scale aggressively. Our data models project the valuation to climb from 1.10 Billion in 2026 to 1.96 Billion by 2033, maintaining a steady CAGR of 8.64% throughout this seven-year horizon.
Segmentation analysis across end-use, capacity, application, power source, and product type
The market segments by end-use into Data Centers, Telecommunications, Power Generation, Industrial, and Other End-Users. Capacity ranges span Low Capacity (Below 50 kW), Medium Capacity (50 kW–500 kW), and High Capacity (Above 500 kW). Applications cover Battery Testing, Uninterruptible Power Supply Testing, and Generator Load Testing, utilizing Diesel, Natural Gas, Battery, and Hybrid power sources across Portable and Stationary product categories.
Regional market analysis and geographic distribution
Geographic performance is heavily concentrated in regions with dense telecommunications networks and advanced industrial automation. North America commands significant market share due to early data center clustering, while the Asia-Pacific region demonstrates the fastest growth trajectory driven by rapid 5G infrastructure rollouts and massive investments in renewable energy storage facilities.
In-depth regional review of key territories
North American growth is underpinned by strict IEEE standards for stationary battery maintenance in critical utility hubs. Meanwhile, European markets prioritize energy efficiency, favoring regenerative load solutions. The Asia-Pacific territory is witnessing unprecedented demand for industrial grade load banks to support surging manufacturing capacities in nations like China and India.
Company profiles and strategic positioning
Industry stalwarts like ASCO Power Technologies and Chroma ATE Inc. focus on high-precision electronic testing gear, whereas firms like Aktif Elektroteknik A.S. and Hunan Fullde Electric Co Ltd. excel in ruggedized industrial manufacturing. Specialized rental providers such as Rentaload SAS capture substantial value by offering flexible deployment options for temporary data center commissioning projects.
Porter's Five Forces analysis of competitive pressures
Bargaining power of suppliers is moderate due to reliance on specialized refractory metals and electronic controllers. Threat of new entrants remains low, hindered by stringent safety certifications and high intellectual property barriers in automated control software. Competitive rivalry is intense, compelling manufacturers to innovate continuously in thermal management and digital integration.
SWOT analysis of the industry ecosystem
Key strengths include high product durability and essential utility compliance requirements. Weaknesses stem from high initial capital outlays for custom-engineered systems. Opportunities abound in the emerging green hydrogen energy sector. Major threats involve fluctuating raw material costs, particularly for aluminum and specialized stainless steel alloys used in resistor elements.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material procurement of alloy resistors and structural steel, progressing through precision manufacturing by firms like REO AG and Telema S.p.A. Integration of digital control systems occurs mid-stream, followed by distribution via direct B2B sales or rental fleets to end-users operating critical power infrastructure in telecommunications and heavy industry.
Investment insights and strategic recommendations
Investors should target companies developing automated, remote-controlled trailer mounted load banks to capitalize on field service labor shortages. Strategic acquisitions of firms specializing in high-capacity regenerative units offer substantial upside, as facility operators increasingly demand sustainable testing methodologies that lower operational carbon footprints.
Conclusion and key takeaways for stakeholders
The Direct Current (DC) Load Bank Market represents a vital, high-growth niche within electrical testing. With a projected valuation of 1.96 Billion by 2033 and a solid CAGR of 8.64%, stakeholders must prioritize software integration, modular mobility, and energy-recovery capabilities to maintain a competitive edge.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are derived through rigorous data triangulation, combining international trade registry shipments, primary executive interviews with key personnel from Eagle Eye Power Solutions LLC and Greenlight Innovation Corporation, and secondary macroeconomic indicators tracking global data center construction expenditures and telecom capital investments.
Scope of the report and coverage parameters
This comprehensive analysis covers global market dynamics for DC load banks from 2026 through 2033. Limitations include potential variances in localized regulatory compliance updates and unforeseen macroeconomic shocks. The report strictly evaluates direct current systems, excluding standard alternating current (AC) load testing equipment unless used in hybrid configurations.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic partnerships between load bank manufacturers and renewable energy developers to test utility-scale battery energy storage systems (BESS). Key players like Dekal Load Banks Pty Ltd. and Sephco Industries Pty Ltd. have rolled out advanced firmware updates enabling wireless load profile programming, significantly enhancing operator safety during high-stress testing procedures.